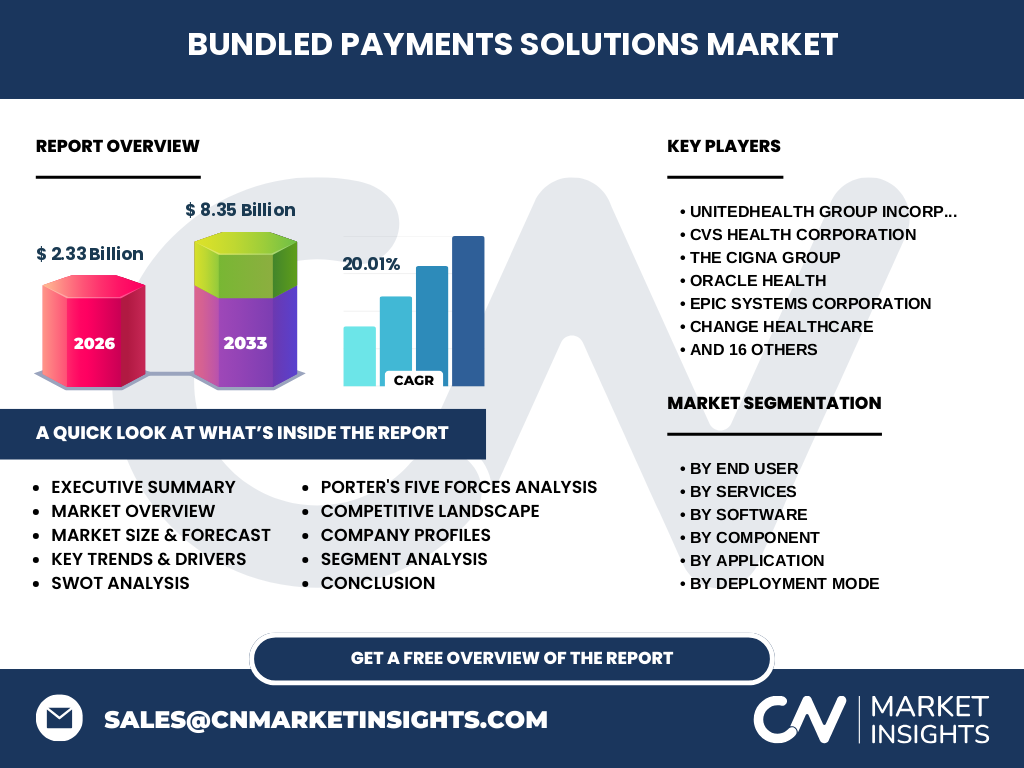
Market overview of the Bundled Payments Solutions Market
Our analysis indicates that the Bundled Payments Solutions Market valued at 2.33 Billion in 2026 represents a paradigm shift in healthcare reimbursement. This sector encompasses specialized software and services designed to manage single-fee payments for entire episodes of care, transitioning providers away from legacy fee-for-service models under stringent Centers for Medicare & Medicaid Services guidelines.
What are the key drivers, restraints, challenges, and opportunities shaping the Bundled Payments Solutions Market?
The market is propelled by regulatory mandates from the CMS Innovation Center emphasizing value-based care. However, interoperability hurdles with legacy electronic health records remain a severe restraint. Opportunities abound for vendors capable of unifying disparate financial workflows across large provider networks.
Emerging trends and growth patterns in the Bundled Payments Solutions Market
Industry trends highlight a rapid migration toward cloud-based architecture to support real-time data exchange among ambulatory surgical centers and large hospital systems. Predictive analytics integration is becoming a baseline requirement for managing post-acute care utilization and mitigating financial downside risks.
COVID-19 impact analysis and recovery trajectory for the Bundled Payments Solutions Market
The pandemic severely disrupted elective procedures, causing a temporary contraction in episode volumes. However, our research shows that COVID-19 ultimately accelerated the recovery trajectory by forcing health systems to adopt robust remote patient monitoring and cost analytics tools to survive revenue volatility.
Competitive benchmarking and strategic dynamics in the Bundled Payments Solutions Market
The competitive landscape features intense rivalry between diversified healthcare giants like UnitedHealth Group Incorporated and specialized tech innovators such as Innovaccer Inc. Market concentration is moderate, with enterprise players leveraging massive data repositories while nimble firms compete on specialized care model design.
Executive summary of the Bundled Payments Solutions Market
Our comprehensive report reveals a robust forecast reaching 8.35 Billion by 2033, expanding at a remarkable CAGR of 20.01% from 2027. Healthcare organizations are rapidly adopting specialized software to navigate complex risk-sharing arrangements, driven by undeniable economic imperatives in value-based care delivery.
Market forecast trajectory from 2027 to 2033
The data projects stellar expansion, surging from the 2.33 Billion baseline in 2026 to 8.35 Billion by 2033. This trajectory reflects a sustained CAGR of 20.01%, underpinned by aggressive payer adoption and expanding mandatory bundled payment initiatives across cardiology and orthopedic specialties.
Segmentation analysis across end users, services, software, and applications
Market segmentation spans critical categories: End Users (Hospitals, Physician Groups, Ambulatory Surgical Centers), Services (Implementation, Consulting, Data Analytics), Software (Claims Processing, Cost Analytics), Components (Software, Services), Applications (Cardiology, Orthopedics, Oncology), Deployment (On Premises, Cloud Based), and Organization Size (Large Enterprises, SMEs).
Regional market analysis and geographic distribution
Geographic performance is heavily concentrated in North America due to advanced regulatory frameworks and mature value-based reimbursement models. However, our analysis indicates emerging momentum in European markets as national health systems seek cost-containment strategies mirroring U.S. alternative payment innovations.
In-depth regional review of key markets
North America dominates demand, driven by stringent CMS penalties and rewards programs. Regional providers are aggressively deploying solutions from firms like Epic Systems Corporation and Oracle Health to streamline multi-provider reconciliation, while APAC shows nascent interest driven by expanding private health insurance networks.
Strategic positioning of leading companies in the Bundled Payments Solutions Market
Industry leaders exhibit diverse strategic positioning: CVS Health Corporation and The Cigna Group leverage integrated payer-provider models, whereas Change Healthcare and Waystar Holding Corp. focus on robust claims processing infrastructure. Specialized entities like agilon health inc. and Privia Health Group Inc. empower physician groups directly.
Porter's Five Forces analysis of competitive intensity
Bargaining power of buyers is moderate to high, as large hospital systems demand bespoke risk and contract management software. Threat of new entrants is mitigated by high regulatory hurdles and complex data security mandates, though nimble cloud-native startups continually challenge legacy architectures.
SWOT analysis of the Bundled Payments Solutions Market
Key strengths include advanced predictive modeling capabilities and strong regulatory tailwinds. Weaknesses involve high implementation costs for small and medium-sized enterprises. Opportunities lie in oncology and cardiology episode expansion, while cybersecurity threats and data privacy regulations pose ongoing strategic threats.
Value chain analysis and industry structure
The value chain flows from raw healthcare data generation—via electronic health records and claims data—through specialized analytics engines provided by companies like MedeAnalytics Inc. and Clarify Health Solutions Inc., ultimately delivering actionable cost insights to payer and provider end-users.
Investment insights and high-potential areas
Our research identifies cloud-based risk and contract management software as a prime investment vector. Venture capital and strategic acquirers should target innovators offering turnkey care model design and automated reconciliation, which directly alleviate administrative burnout for overburdened physician groups.
Conclusion and key takeaways for stakeholders
The Bundled Payments Solutions Market is transitioning from an experimental framework to a core healthcare operational necessity. Achieving a CAGR of 20.01% through 2033, success in this sector requires seamless software integration, deep clinical analytics expertise, and alignment with evolving payer-provider risk models.
Research methodology and data triangulation
Baseline estimates are meticulously triangulated by combining exhaustive trade registry data, primary stakeholder interviews with healthcare executives, and secondary macroeconomic indicators from federal health agencies. This rigorous validation ensures high-fidelity market sizing and accurate growth projections.
Scope of the report and coverage parameters
This report covers global deployment across software and services categories, evaluating hospitals, physician groups, and ambulatory settings. Limitations exclude unverified regional pilot programs and purely fee-for-service administrative billing platforms that lack episode-of-care risk-sharing capabilities.
Recent developments, partnerships, and strategic moves
Recent market activity is defined by aggressive strategic partnerships between tech platforms like Innovaccer Inc. and provider enablement firms such as Vytalize Health Inc. These collaborations focus on embedding real-time cost analytics directly into clinical workflows to capture maximum shared savings.